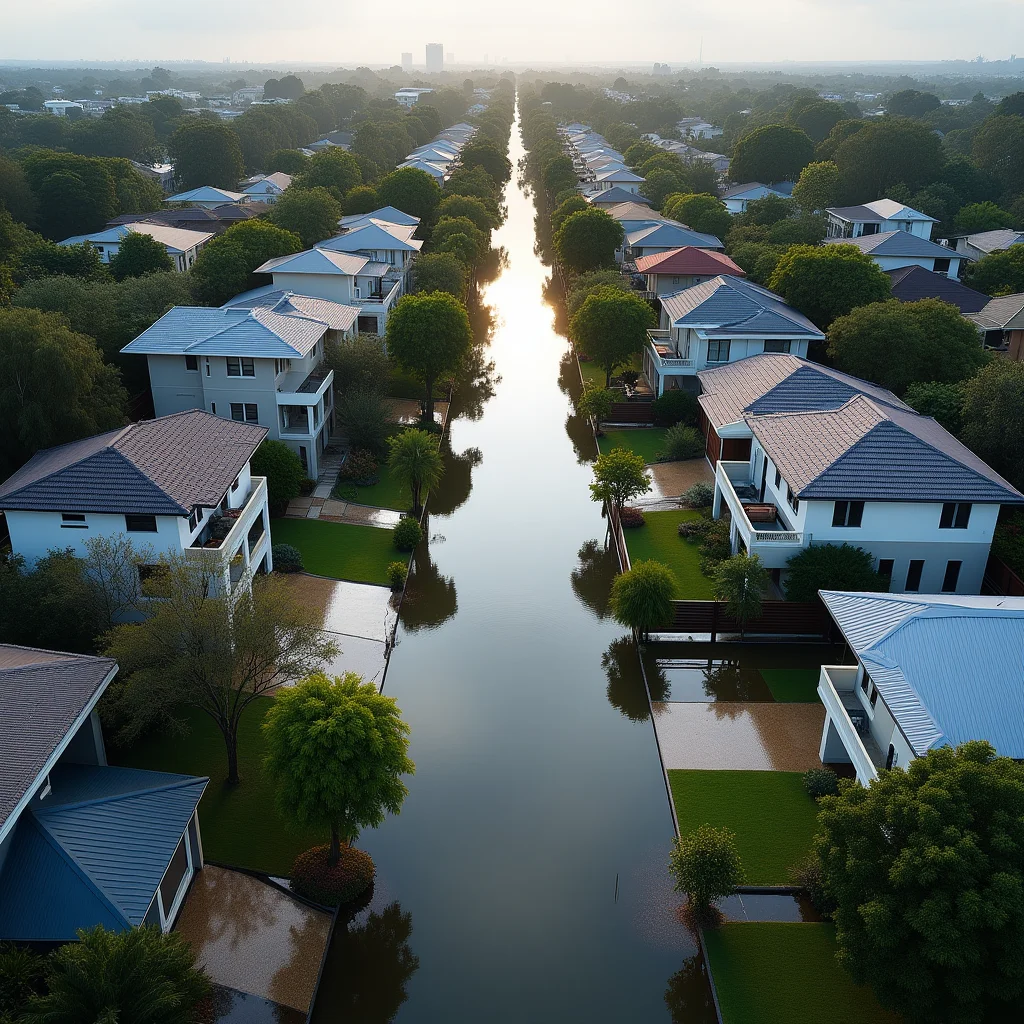
Strata insurance is compulsory for every residential strata scheme in Australia, yet a significant proportion of apartment and townhouse owners remain uncertain about what the policy actually protects — and, critically, what it leaves entirely uncovered. Understanding this distinction is one of the most practical steps any strata owner or investor can take to protect their asset.
What Strata Insurance Is Required to Cover
In every Australian state and territory, owners corporations (also called bodies corporate in Queensland) are legally required to hold strata building insurance over the shared structure. The policy must cover the building itself — external walls, the roof, common-area infrastructure, lifts, stairwells, and shared facilities such as swimming pools and car parks. It must also include public liability cover for injuries or property damage occurring in common areas. These requirements are embedded in strata legislation in each jurisdiction, meaning the obligation sits with the collective owners corporation, not with individual lot owners.
The practical effect is that the building's structural integrity is insured collectively. If a fire damages the roof or a burst pipe floods a common corridor, the strata policy responds. This is a meaningful protection, particularly for apartment owners who share walls, ceilings, and floors with neighbours and have no ability to individually insure a structure they don't solely own. Premiums are pooled across all lot owners through levies, which means larger and higher-risk buildings spread that cost more broadly. For a comprehensive breakdown of how levy structures and owners corporation governance works, see the APF guide on Strata Title vs Torrens Title Explained.
For investors assessing the true running cost of a strata property, it is worth factoring strata insurance levies explicitly into yield calculations. Buildings in flood-prone postcodes, those with ageing infrastructure, or high-rise towers with expensive common facilities can attract materially higher premiums, which flow directly into quarterly levies. These costs are deductible for investment properties, which connects to the broader tax treatment of strata ownership — for context on how property investment deductions work, see Negative Gearing Explained.
The Significant Gaps: What Strata Insurance Does Not Cover
The most common and costly misunderstanding in strata ownership is the assumption that the building policy covers everything inside a lot. It does not. Strata insurance typically does not cover the contents of individual units — furniture, appliances, electronics, clothing, and personal belongings. It also commonly excludes internal fixtures that were added or upgraded by individual owners after the original construction, such as custom kitchen cabinetry, bathroom tiles, or floor coverings that exceed the building's standard specification. The precise boundary between what is "building" and what is "contents" or "owner-installed improvement" varies between policies and between states, and this ambiguity regularly produces disputes at claim time.
Liability inside the lot is another gap. If a guest slips inside your apartment, the strata public liability policy covers common areas — not your front door inward. Individual owners need their own contents and liability cover for events originating inside the lot itself. For investors who rent their property out, this gap is even more pronounced. A standard strata policy provides no cover for loss of rental income, no cover for malicious damage by tenants, and no cover for legal costs associated with tenancy disputes. These risks require a separate landlord insurance policy — and the two policies must sit alongside each other, not substitute for each other.
Investors managing strata properties should also be aware that many strata policies exclude certain types of water damage — particularly gradual leaks, condensation, or slow-developing defects — even when they originate in common-area infrastructure. These exclusions are frequently buried in product disclosure statements and only become apparent at claim time. Reviewing the policy schedule obtained through your owners corporation annually, and requesting a copy of the full PDS, is a straightforward safeguard that many owners skip. For a broader view of property market data relevant to strata investment returns, REAStats tracks strata-heavy markets across major Australian cities.
Common Exclusions Strata Owners Encounter
Beyond the contents-versus-structure distinction, strata policies across Australia carry a range of standard exclusions that catch owners off guard. Flood — defined precisely as water inundation from an external natural source — is excluded from many standard strata policies, particularly in older schemes that have not updated their coverage. Strata committees in flood-affected postcodes should specifically verify whether flood cover has been added as an endorsement, as the default position is often exclusion. This is especially relevant in parts of Queensland, northern New South Wales, and Victoria where flood risk has escalated in recent years.
Defective workmanship and building defects present a separate and growing challenge. Strata insurance is not a substitute for a builder's warranty or a home warranty insurance scheme. If a building develops structural cracking, waterproofing failures, or fire-safety non-compliance arising from original construction defects, the strata policy will generally not respond — the claim path lies with the builder, their insurer, or state-based statutory warranty schemes, each of which has its own limitation periods. Purchasers of newer strata properties, particularly those buying off the plan, should obtain independent building and pest inspections and understand the applicable statutory warranty period in their state before settlement.
Short-term rental use through platforms such as Airbnb introduces another exclusion risk. Most strata building policies are written on the assumption of standard residential occupation. Where a lot owner operates short-term rental without notifying the insurer or owners corporation, the policy may be voided for claims arising from that lot. Some strata schemes have moved to amend by-laws to restrict or regulate short-term rental specifically because of this insurance exposure at the whole-of-building level. Owners considering short-term letting should seek written confirmation from both their personal contents insurer and through the owners corporation that the building policy remains valid under their intended use.
Practical Steps for Strata Owners and Investors
Every strata owner — whether owner-occupier or investor — should take three specific actions to understand their actual insurance position. First, obtain the current strata insurance certificate of currency and the full policy PDS from the owners corporation or strata manager. Review the schedule of covered events, the definition of the insured building, and the exclusions list. Second, take out a separate contents policy for the lot's internal fixtures, fittings, furniture, and personal property — and ensure the sum insured reflects the genuine replacement cost of owner-installed improvements, not just standard builder's fittings. Third, if the property is tenanted, hold a dedicated landlord insurance policy that covers loss of rent, tenant damage, and landlord liability. For a deeper guide on this layer of cover, the APF's Property Insurance Guide sets out what Australian landlords need and where policies commonly fall short.
For investors assessing strata properties as part of a broader portfolio strategy, the insurance cost structure is a legitimate due diligence item. High levies driven by large insurance premiums can meaningfully reduce net rental yield, particularly in buildings with ageing plant, high-risk locations, or a history of claims. Requesting the last two years of owners corporation meeting minutes before purchase will reveal whether the committee has faced premium increases, claims disputes, or policy gaps — information that rarely appears in the marketing materials but is directly relevant to the investment case. Understanding the difference between strata and freehold title — and its insurance implications — is also addressed in the APF guide on Strata Title vs Torrens Title.
Strata ownership offers genuine advantages — shared maintenance costs, pooled capital for major works, and often lower entry prices in well-located urban areas. But those advantages come with an insurance structure that is more layered and more exclusion-prone than most owners appreciate at the point of purchase. Taking the time to understand what the collective policy covers, where it stops, and what individual policies must fill in, is not optional maintenance — it is fundamental ownership literacy for the nearly one-third of Australians who now live in strata-titled properties.
This article was produced with AI assistance and reviewed for accuracy. Content is for informational purposes only and does not constitute financial or property investment advice.