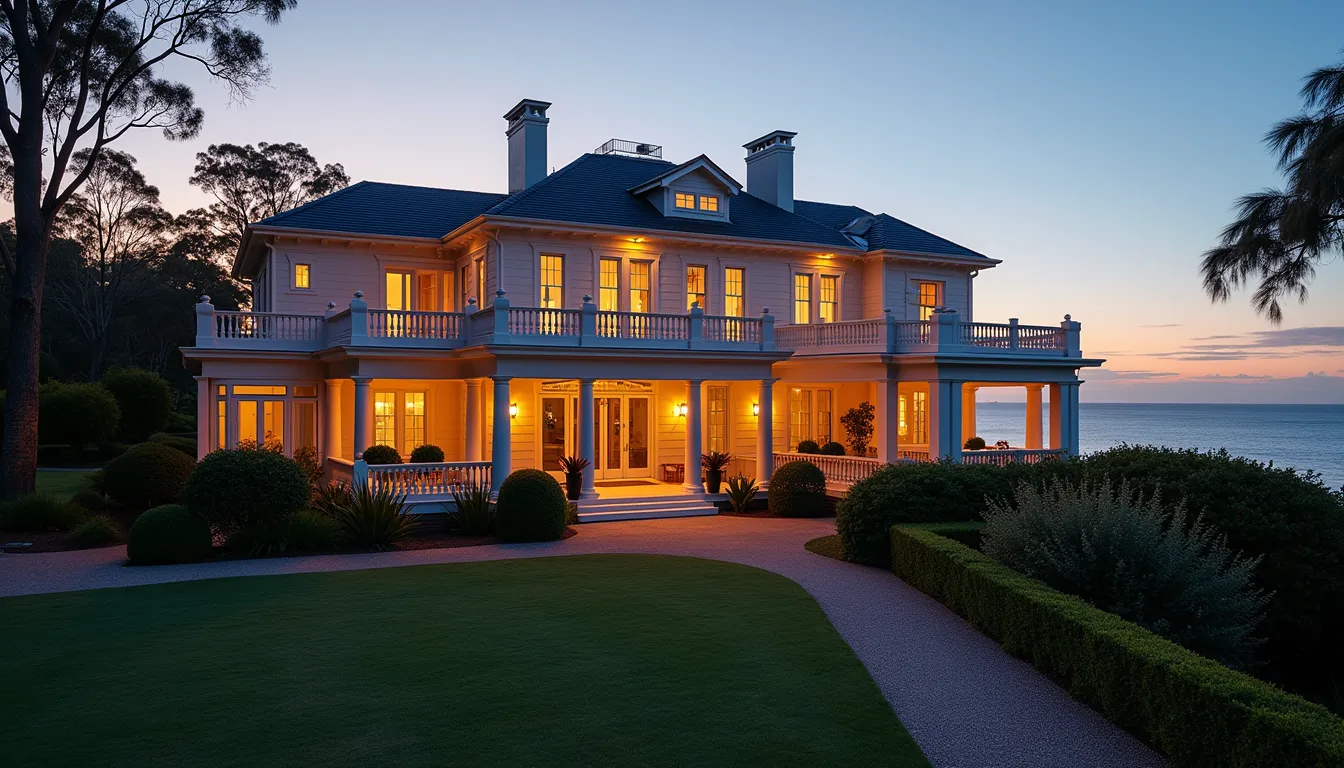
According to realestate.com.au, the family of late businessman Wallace Cameron has listed his Middle Crescent, Brighton, mansion with a $12.25m-$13.475m price guide, a figure below the $13.75m the Camerons paid for the property in July 2023. It is the fourth high-profile loss across the late executive's property portfolio, following an earlier episode in which a Cameron-owned Portsea weekender burned down mid-sale before settlement could be finalised.
The Brighton Listing and a Pattern of Losses
The Middle Crescent home sits next door to the Italianate mansion Shane Warne once brought Elizabeth Hurley to, according to realestate.com.au. Kay & Burton agent Matthew Pillios is handling the listing via expressions of interest, with offers due to close on December 10. The five-bedroom, five-bathroom residence spans an 833sq m block and includes a 12-car basement garage, a basement cinema, a games room with a bar, and a wine cellar with a tasting area — described by Pillios as one of the best examples of architect Martin Friedrich's work in the suburb.
Related reading: REAStats property market data.
This is not an isolated dip for the Cameron property ledger. The family's $25m purchase of the Zagame family's Kent Ave home in Brighton in 2021 was sold two years later for $24.5m. Their Sefton estate at Mt Macedon, bought for $8.175m in 2005 and listed with a disclosed $12m reserve in 2010, ultimately sold for $5.25m in 2017. And the Franklin Rd, Portsea, weekender — listed in 2021 for $8.5m-$9.5m and under contract around $8m by 2023 — burned down before settlement, with the deposit refunded. It was eventually sold for $3.95m, about 60 per cent of the $6,293,250 the Camerons had paid for it in 2008.
Why a Mid-Sale Fire Matters for Settlement Risk
In the Portsea case, the deal collapsed and the deposit was refunded.
Three of the four properties cited in the listing — Kent Ave, Sefton at Mt Macedon, and the current Middle Crescent listing — involve straightforward resale losses with no insurance event at all. That distinction matters: market timing risk and insurable-event risk are separate exposures, and only one of the four Cameron losses stemmed from physical damage rather than price movement.
Background: Settlement, Risk and Title
For a full walkthrough of how contracts, inspections, finance and legal obligations fit together across that window, see Conveyancing Explained — The Australian Property Settlement Process.
Buyers weighing a Torrens title mansion against a strata apartment should understand how those insurance responsibilities diverge; see Strata Title vs Torrens Title Explained.
Practical Implications for Buyers and Owners of Prestige Property
For prospective buyers of properties in the Cameron portfolio's price bracket, the lesson is less about insurance fine print and more about timing discipline. Anyone transacting on a $8m-$13m-plus asset should confirm with their conveyancer exactly when their insurable interest begins and ensure cover is bound simultaneously.
Financing considerations also differ at this price point. Whatever the financing path, the Cameron sale history is a reminder that prestige property carries its own distinct risk calculus, one where insurance timing and market timing both demand equal attention. For a broader grounding in cover types relevant to any Australian property purchase, see our Property Insurance Guide.
Further reading
This article was produced with AI assistance and reviewed for accuracy. Content is for informational purposes only and does not constitute financial or property investment advice.