According to realestate.com.au, correction warnings have been issued for 56 major areas around the country, with owners told that even larger home value falls are on the way. As listings surge across these markets, the timing raises an urgent question that many landlords have not yet asked themselves: does your insurance policy actually protect you when market values fall?
What a Market Correction Does to Your Landlord Insurance Coverage
The surge of new listings across 56 flashpoint areas identified by realestate.com.au is more than a pricing story — it is an insurance story. When property values fall sharply, the gap between a home's insured value (typically the sum insured for building replacement) and its actual market value shifts in ways that catch landlords off guard. Most landlord insurance policies are structured around replacement cost or agreed value, not market price — but owners who have not reviewed their sum insured in several years may find themselves either over-insured (paying premiums on inflated valuations) or, more dangerously, under-insured if rising construction costs have outpaced their last policy review.
For additional market context, see REAStats property market data.
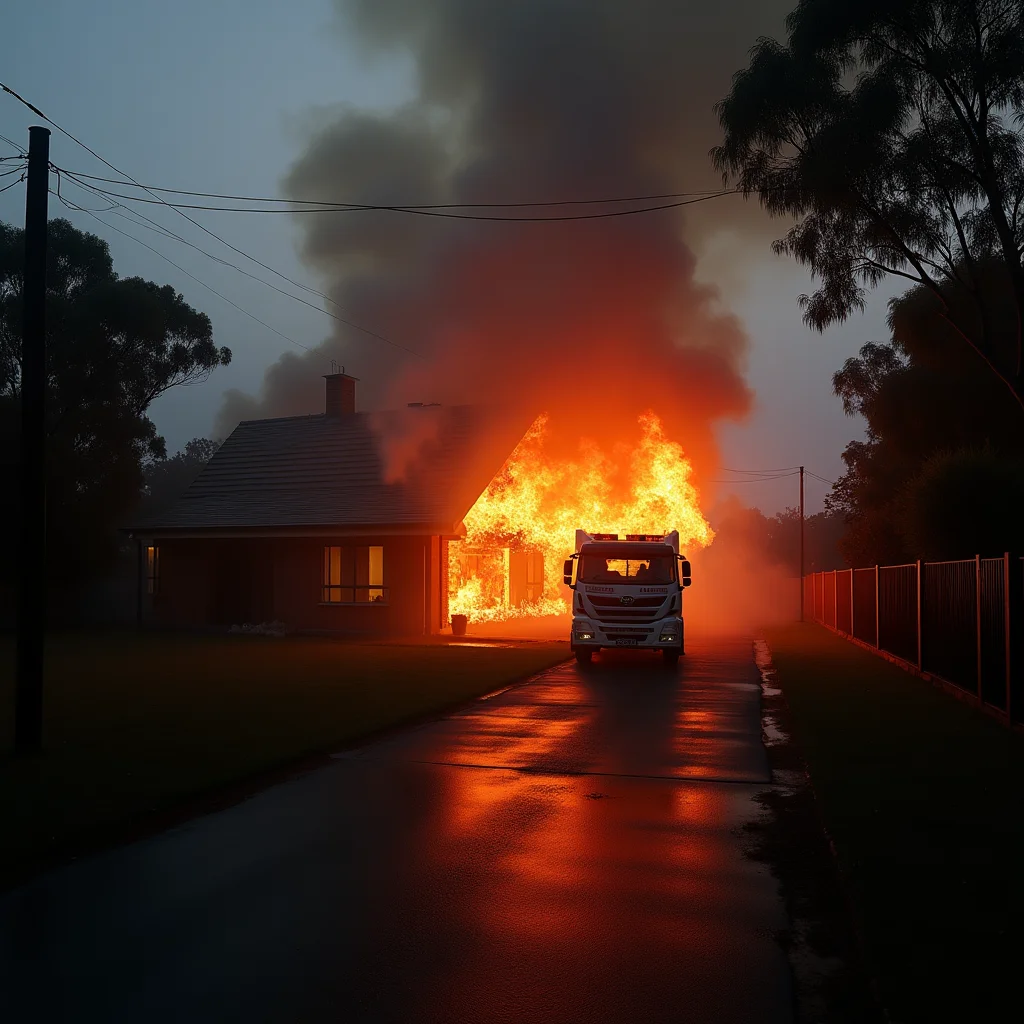
Under-insurance is the more common and more damaging outcome. Where a policy was last reviewed some years ago but replacement costs have climbed due to persistent construction inflation while the property's market value has simultaneously declined, the insured sum may no longer reflect what it would actually cost to rebuild. In a falling market where investors are already under financial pressure, a shortfall between the insured sum and actual replacement cost can mean a partial payout on a fire or storm claim — an outcome that can be catastrophic for landlords with limited financial buffers.
The practical implication is immediate: investors in any of the 56 affected markets should commission a fresh building replacement cost assessment — not a market appraisal, but a quantity surveyor report or insurer-endorsed valuation focused on what it would cost to demolish and rebuild the structure. It is a prudent outlay against the risk of a significant shortfall in the event of a major claim. For a comprehensive overview of what landlord policies cover, see our Property Insurance Guide.
Falling markets can create compounding insurance vulnerabilities. When prices fall and financial pressure mounts, owners may be tempted to reduce premiums by cutting coverage — creating greater exposure at precisely the moment when their financial buffers are thinnest. Reviewing coverage adequacy during a correction, rather than deferring it, is the more protective course of action.
Rental Income Protection: The Coverage Landlords Are Most Likely to Miss
Beyond building coverage, the correction warnings across these 56 markets expose a second landlord insurance gap: loss of rental income cover. As listings surge and prices fall, vacancy periods lengthen. Tenants become harder to place and, in some softer markets, existing tenants may seek rent reductions or vacate entirely. Standard building-and-contents policies do not cover loss of rental income unless a specific landlord insurance rider or standalone policy is in place. Even then, the conditions attached to rental income claims are stringent — cover typically applies only when loss of income results from an insured event (fire, flood, malicious damage), not from general market softness or a tenant simply leaving.
This distinction matters enormously. An investor holding a property in one of the 56 identified correction zones who loses a tenant and cannot re-let for an extended period will receive nothing from a standard policy. A landlord insurance policy — a distinct product from standard home and contents cover — will typically provide rent default cover (where the tenant stops paying), rent loss following an insured event, and in some cases, legal costs for tenant disputes.
For investors assessing their exposure across the affected markets, the checklist is straightforward: confirm whether your existing policy is a true landlord insurance product (not a standard home insurance policy with a rental endorsement), check the maximum weeks of rent loss cover provided for insured events, and verify the rent default sublimit — many policies cap this at a relatively small number of weeks, which may be insufficient if a legal eviction process drags out over several months. Tracking vacancy rate trends by suburb can help investors benchmark realistic re-letting timelines before a vacancy occurs.
Background: Why Falling Markets and Insurance Risk Go Hand in Hand
Property investors often treat insurance as a fixed background cost — something renewed annually without review. In a rising market, this approach is relatively low-risk because property values, construction costs, and rental income all tend to move upward together, broadly maintaining coverage adequacy. But in a correction — particularly one flagged across as many as 56 distinct areas simultaneously — the picture shifts. Maintenance deferred during a downturn increases the likelihood of insurable events; financially stressed tenants may be more likely to default or cause damage; and insurers in high-claim regions can and do revise policy terms at renewal, sometimes excluding specific risks (such as flood or storm surge) in areas they deem elevated risk.
Understanding the title structure of your investment property also affects insurance obligations. As detailed in the APF guide on Strata Title vs Torrens Title, strata-titled properties have their building insurance managed by the owners corporation — individual investors in a strata scheme do not purchase building insurance separately. However, strata building insurance does not cover contents, landlord liability, or rental income loss — all of which require a separate landlord policy. Investors who assume their strata levies include comprehensive landlord protection are routinely surprised at claim time. For investors unfamiliar with how a buyer's agent can help identify insurance-risk properties before purchase, see the APF guide to What is a Buyer's Agent?
What Investors in Correction Zones Should Do Now
The realestate.com.au warning covering 56 major areas is a trigger for action, not just monitoring. Investors holding property in any flagged
This article was produced with AI assistance and reviewed for accuracy. Content is for informational purposes only and does not constitute financial or property investment advice.